

One bad storm or one burst pipe can erase a year of rental profit. The repair bill is only part of it. The size of your insurance payout, and how fast it arrives, often decides whether a loss is a bad month or a bad year.
According to the Insurance Information Institute (Triple-I), roughly 1 in 67 insured homes files a property claim in a typical year, and water damage and freezing made up 22.6% of homeowners claims in 2023. Rental owners face the same odds with thinner margins and a tenant waiting on answers. This guide covers the first 30 days after a loss, where carriers tend to come up short, and when outside help pays for itself.
Why a Property Claim Hits Rental Cash Flow Harder
A homeowner with a damaged roof lives with the problem. A landlord loses income. Every vacant week is rent you won’t collect, the deductible applies per building, and the next renewal may come with a higher premium. Landlord policies already run about 15-25% above comparable homeowners coverage, according to an estimate from insurer Steadily, so a claim can sting twice.
That’s why the settlement number matters as much as the repair. Many owners who suspect the first offer is too low turn to public adjusters in Ohio, licensed professionals who work for the policyholder rather than the insurance company. They don’t replace your contractor or your agent. Their job is to build the claim and push back on the carrier’s scope and pricing.
Ohio gives landlords plenty of reasons to be prepared. State Farm’s March 2026 storm update listed Ohio among the states with its highest claim counts, with hail and wind the most common causes.
The First 72 Hours: Protect the Property and the Paper Trail
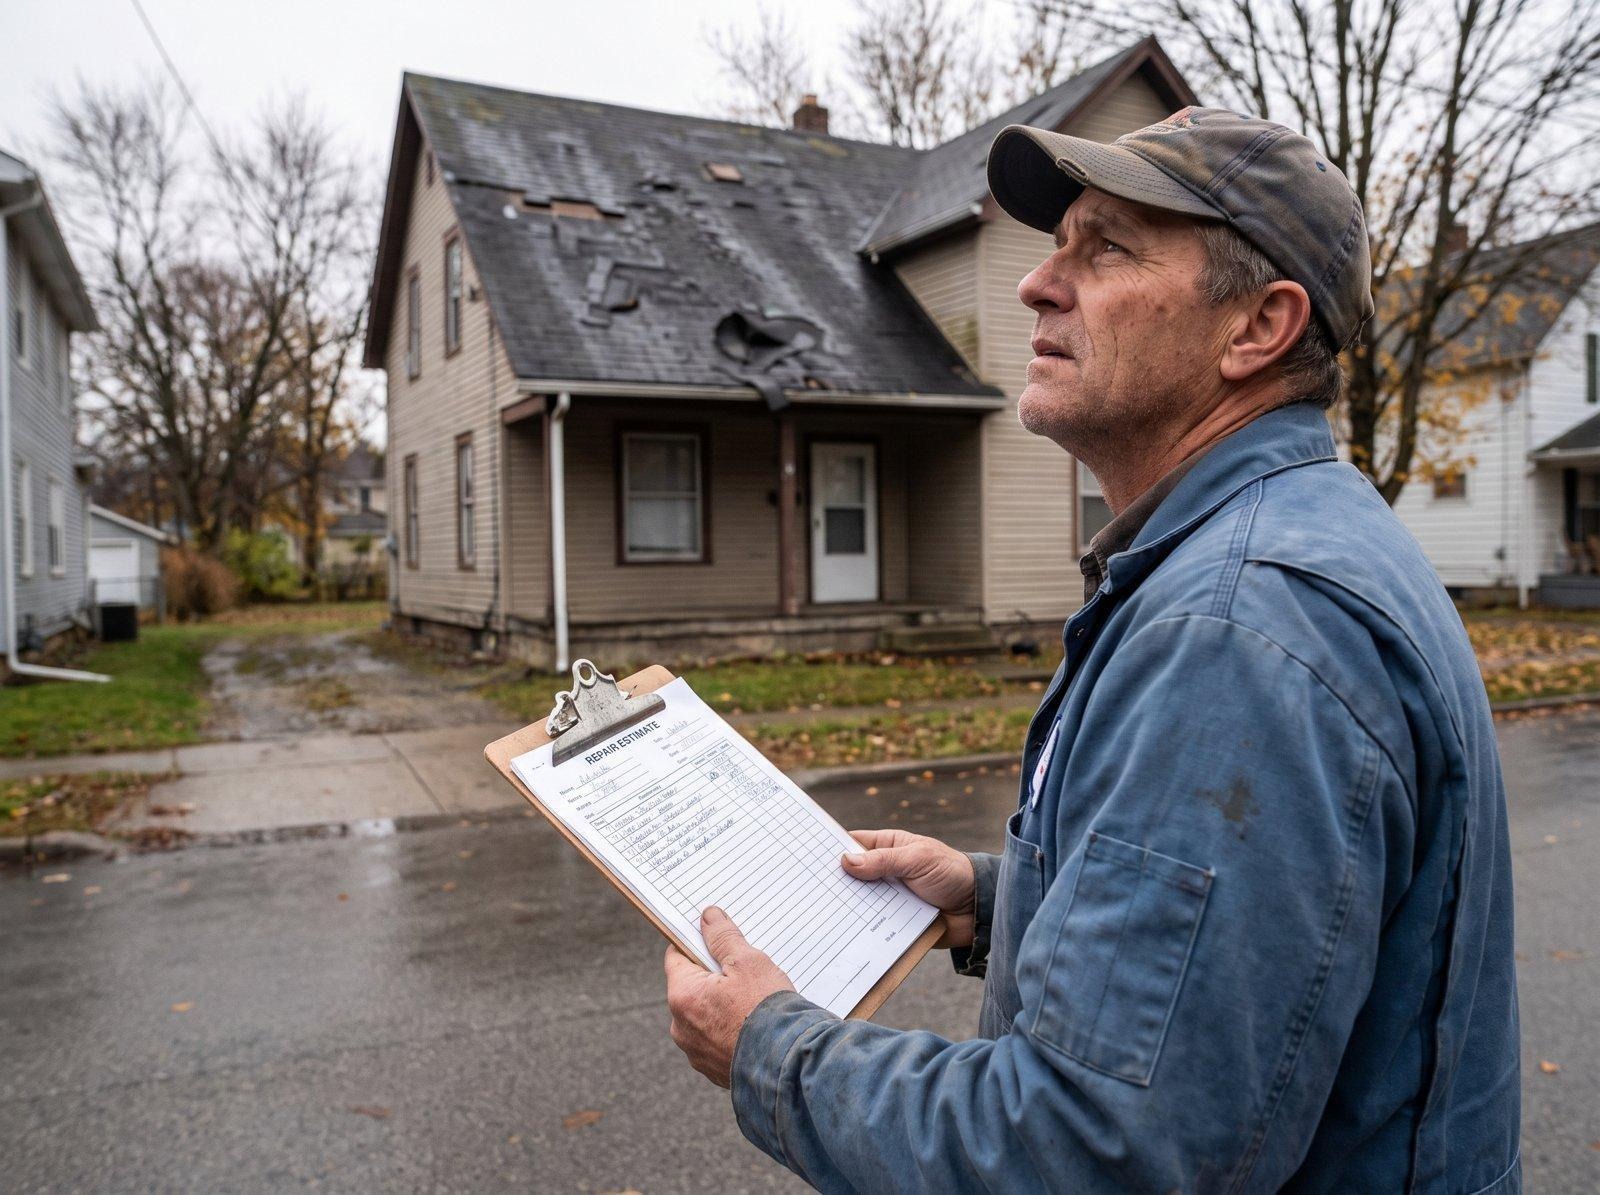
Stop the damage first. Tarp the roof, shut off the water, and start extraction. Keep every receipt, because reasonable mitigation costs are generally part of the claim. Then document everything before anyone moves a thing: wide shots, close-ups, serial numbers on damaged appliances, and video walk-throughs of each affected unit.
Report the loss to your carrier quickly, and write down the date, time and name of every person you speak with. Tell your tenants what’s happening and what they should do about their own belongings. Their renters policy, if they have one, handles their property; yours handles the building.
Our emergency roof repair checklist walks through the inspection report, photo and video steps in more detail. If water is involved, read our piece on how a leak can turn into a lawsuit before you talk to anyone about fault. And know your rights as a policyholder: the Ohio Department of Insurance explains consumer claim protections and takes complaints.
Where Landlord Claims Go Wrong
The costliest habit is accepting the first estimate. Adjusters working for the carrier are doing a job, and that job isn’t to maximize your payout. Common trouble spots include:
Gradual-leak and mold exclusions that the carrier applies broadly
Scope disputes, such as paying to repair a few shingles when the roof section can’t be matched
Slow responses that stretch a repair into a vacancy
Lost rent that’s undervalued or left out entirely
One Ohio homeowner, as Moneywise reported, was offered repair of only three shingles after a March 2025 hail storm. It’s a single case, not a trend, but it shows how far an opening offer can sit from a real fix. Disputes are common enough that NPR covered lawsuits over hail payouts in April 2026.
Premiums are part of the picture too. Ohio customers saw a 10.9% premium increase last year, per the Ohio Insurance Agents Association as reported by WCPO, so an underpaid claim you can’t fix is more expensive over time than it looks today.
When a Licensed Adjuster Is Worth the Fee
Hiring help isn’t always the right call. A small, clean claim that the carrier pays quickly doesn’t need it. Consider an adjuster when:
The loss is large, or involves fire or several units
The claim has been denied, delayed or partly paid
The carrier’s scope doesn’t match your contractor’s bid
You don’t have the time to manage the back-and-forth
Public adjusters typically charge a percentage of the settlement, so get the contract in writing and ask exactly what’s covered. Confirm the license with the Ohio Department of Insurance before signing; Ohio requires applicants to post a surety bond and pass an exam. Ask whether they’ve handled landlord policies and loss-of-rent claims, since those differ from a standard homeowner file.
If a dispute remains, your policy’s appraisal clause or an insurance attorney may be next. An adjuster is usually the cheaper first step, and it can resolve the gap before things get that far.
A Landlord’s Claim Checklist
Most of the work happens before a loss. Keep these in place:
A current copy of every policy, with deductibles and exclusions flagged
An inventory of each unit, with dated photos
Maintenance records, especially for roofs, plumbing and water heaters
A short list of vetted mitigation and repair vendors
A reserve fund sized to at least one deductible, plus a month of lost rent
Roof condition matters here too. Our look at how roof condition affects rental value shows why records of upkeep help both a claim and a sale.
Treat Claims as a Cash-Flow Decision
A claim isn’t just paperwork after a bad day. It’s the part of the loss you can still influence. Document early, question any estimate that doesn’t match your contractor’s, and bring in a licensed advocate when the gap between the two is large enough to hurt your returns.